Monday, 4 May 2020

Why I Don’t Regret Moving Back to New York City—Coronavirus and All

franckreporter/Getty Images

Right now, I’m on Day 30- or 40-something of lockdown with my husband and two grown kids in New York City, looking out at deserted streets.The only traffic outside consists of ambulances and Amazon Prime delivery trucks.

I’d grown up in NYC, but moved out to the nearby suburbs when my kids were young.

A year ago, with our college-age kids nearly out of the nest, we moved back to the Big Apple, excited by this city’s promise of midlife reinvention. It was time for a change.

And at first, it was good—really good—being able to walk everywhere unencumbered by a car, meeting friends for dinners out (“You want Malaysian or Nepalese tonight?”) without the worry of catching the last commuter train back to the ‘burbs. I realized how much I’d missed New York City.

That was before coronavirus arrived, and changed everything.

Now, it’s terrifying and tragic here, although so far, at least, I am lucky: Neither I nor my immediate family has contracted COVID-19, which has taken the lives of more than 13,000 souls here.

To be healthy in the epicenter of a pandemic means I have nothing to complain about.

Like many New Yorkers, I’ve gotten a flurry of calls and texts from friends and family urging me to flee the city. Some go so far as to ask, point-blank, whether I regret that I so recently moved here.

Many people assume that I must miss my old house in the suburbs, which I’d recently sold. That I miss its yard and garden, which I could be tending right now without a mask covering my face. Or miss stretching my legs in front of my old fireplace, without the fear of pressing the elevator buttons of the high-rise I live in now, which might be covered in COVID-19.

Who, at this tragic time, wouldn’t miss their old life in the ‘burbs, and regret their decision to move to NYC?

But here’s the truth: I have no regrets, and don’t want to leave. Here’s why.

Reason 1: The virus isn’t a city-centric germ

As the pandemic took root in New York City, concerned friends in faraway places texted, “You need to GTFO now!”

I lay awake at night, wondering if they were right, thinking of my city pals who’d quite literally headed for the hills.

A dear friend who had flown to Florida to take care of relatives when the pandemic began kindly offered me her house in the ‘burbs. Her desire was to give me and my family relief from the oppressive tsunami of anxiety in the city.

But I realized it would be the same stress, different Zip code. The supermarket would still feel like a scene out of a terrifying virus movie, in the vein of “Contagion” or “Outbreak.”

I would still be fighting for FreshDirect delivery slots and frantically swabbing everything down with disinfecting wipes. COVID-19 is an awful, equal-opportunity disruptor around the globe.

Much as I was touched by my friend’s offer, I chose to stay put.

Reason 2: I am loyal to NYC healthcare

Even when I moved to the suburbs, I kept most of my NYC doctors for continuity and because I think (translation: I know) they are the best of the best.

I was commuting in daily for my job anyway, so it made sense.

I’ve been seeing these M.D.s for years, so if I or a loved one were to get sick, I’d know who to call and believe that I could get good treatment.

In the suburbs, the idea of being in a small community with a small, easily overwhelmed hospital wouldn’t offer much comfort.

And although the NYC medical system has been strapped and stretched to the limit, I take heart in the thousands of retired frontline workers who have stepped up, as well as the ready-to-graduate medical school students who are joining the fight and the plane-loads of workers from elsewhere across the country who flew here to help.

Reason 3: Despite what you’ve heard, there is nature in New York City

“You sure must miss your yard right now,” a friend said when asking whether I was doing OK in NYC. Damn straight, of course I do!

The lilacs my husband planted for me must be gearing up to bloom; the lilies of the valley are probably perfuming the air; and the cardinals, chipmunks, and baby bunnies are likely frolicking in true Disney-esque fashion.

That said, we were never those “spend the day in the backyard” kind of people. That’s part of the reason we moved.

And even in NYC, I can still get a nice hit of nature, even at this grim time. Once properly masked and gloved, I can walk around and see spring unfold in local parks.

The ornamental pear trees nearby bloomed bright white, daffodils are still swaying, and the cherry blossoms are falling to the ground, like crepe paper underfoot after a high-school dance.

Is it as good as a glorious suburban half-acre? The city-person answer is: absolutely.

Reason 4: My city roots run crazy-deep

Other than my sojourn in the suburbs, NYC is the only place I’ve lived. I was born here, educated here, got married here, gave birth here. All members of my small family are here.

As we reached the peak of the outbreak, I engaged in catastrophic thinking at 2 a.m., wondering if the bridges and tunnels might get sealed off, as they were on 9/11.

If that were to happen, I did not want to be on the other side in the ‘burbs.

I wanted to feel as if I could walk or bike my way to my mother and sister, who were also inside the NYC perimeter.

I did not want to be stuck on the porch of my lovely suburb house, wondering how they were. It’s not just where you live, it’s who lives nearby.

Reason 5: I want to be on the ground and on the grid

Maybe you’ve watched Gov. Andrew Cuomo give his daily talks, and refer to our being “New York Strong.”

People who live in the city have made the choice to live somewhere very intense and very stressful.

For whatever reason, we flourish when packed together in tight spaces; it’s some kind of foxhole-bonding that I’ll leave to the sociologists to fully explain, but here’s my take.

Being a New Yorker forces you to engage with the dark truth of the situation. It compels you to support those less fortunate. My family, like so many others, has donated food to the frontline workers and held fundraisers for charity.

And then there is the clapping every evening at 7 p.m.—a daily wellspring of joy where New Yorkers open the windows wide and whoop and bang pot lids together.

It’s an expression of thanks for the frontline workers who risk their lives to care for the sick, and an expression of hope. Every day, new voices join. Every day, the roar gets louder.

For me, this is the essence of what I love about New York City, or any city really—being thrown together with strangers and finding common ground.

We’re here for the good times, and we’re here for the bad. And we’re going to be in it, and get through it, together.

The post Why I Don’t Regret Moving Back to New York City—Coronavirus and All appeared first on Real Estate News & Insights | realtor.com®.


source https://www.realtor.com/news/trends/why-i-dont-regret-moving-to-nyc-covid-19-and-all/

Tommy Lee Takes Another Spin at Selling His Rockin’ Calabasas Compound

The Agency; Steve Granitz/WireImage

Mötley Crüe drummer Tommy Lee is still looking to drum up a sale of his rockin’ crib in Calabasas, CA. It can be yours for $4.59 million.

That’s slightly less than two years ago, when the home was priced at $4.65 million. At the current ask, the home is over 20% less than the $5.85 million the drummer paid for the place back in 2007.

Built in 1987, the musician’s home has been on and off the market since 2016, when Lee first offered the melodious mansion for $6 million. The sprawling spread contains some amazing amenities, which will eventually strike the right chord with a buyer.

And Lee’s made some improvements to the place, including an entirely new roof, as well as updated master spa finishes, notes Emil Hartoonian of The Agency, the listing agent.

“This is a very unique offering in Calabasas,” says Hartoonian. “The home was built and owned by the developer for all of Vista Point in Calabasas. Since it was built as a developer’s personal residence, the quality is unparalleled and is on one of the best lots in the community.”

Hartoonian also highlighted an area of the home that he’s particularly enamored with.

“The retractable roof atrium in the middle of the home is a spectacular tropical escape,” he says.

Atrium

Courtesy of The Agency

Family room

Courtesy of The Agency

Chef’s kitchen

Courtesy of The Agency

Home theater

Courtesy of The Agency

Recording studio

Courtesy of The Agency

Pool

Courtesy of The Agency

The home measures almost 10,000 square feet, with six bedrooms and eight bathrooms. The layout flows around a three-story atrium with lush plantings, a koi pond, and a retractable, open-air roof, allowing natural light to illuminate the interiors. Set atop a hillside, the property also offers views of the city’s lights.

Other amenities include a chef’s kitchen with center island and granite counters, a living and dining room, and a library or office with a terrace.

The lavish main-level master suite features glass doors that open to the pool, as well as a large, walk-in closet, and a master spa.

On the lower level, the home hits another high note. The space owned by a rock god, naturally, includes a professional recording studio with isolation booths and a control room. 

The home screening room, which features a concession bar, is sure to delight, and it also has a dining and wine-tasting area.

To complete the compound, the garage has space for parking and ample storage. This time around, someone will want to make it their “Home Sweet Home.”

The post Tommy Lee Takes Another Spin at Selling His Rockin’ Calabasas Compound appeared first on Real Estate News & Insights | realtor.com®.


source https://www.realtor.com/news/celebrity-real-estate/tommy-lee-rockin-calabasas-compound-back-on-the-market/

Applying for a Mortgage? Good Luck! Coronavirus Has Made It Harder To Qualify

Getty Images; realtor.com

It’s a stark good news, bad news story. The good: The lowest mortgage rates in recorded history are motivating many would-be home buyers and refinancing homeowners to seek out a loan. The bad: Amid the economic upheaval caused by the novel coronavirus, it’s become significantly more difficult to get one of those loans.

As more Americans are getting furloughed and pink-slipped, lenders—ever mindful of the housing bust of more than a decade ago—are requiring higher credit scores and larger down payments. Some have ceased making loans they consider riskier, such as those for self-employed borrowers and real estate investors; those that require lower credit scores and down payments; and those for larger amounts, such as jumbo mortgages. Or they may be jacking up fees to make the loans prohibitively expensive.

That will mean that some folks who still want to go ahead and take advantage of those record-low mortgage interest rates won’t be able to do so. Rates fell to just 3.23% on a 30-year fixed-rate loan for the week ending April 30, according to Freddie Mac.

That’s the lowest it’s been since Freddie Mac began tracking rates in 1971.

Yet the availability of mortgage credit dropped 16.1% in March—a clear indication that lending standards are tightening up, according to the Mortgage Bankers Association’s Mortgage Credit Availability Index. That’s the lowest level of the index since mid-2015.

Lenders have reasons to be cautious. Roughly 7% of mortgages were in forbearance as of April 19, according to the MBA. Experts predict the number of homeowners unable to make loan payments due to economic hardship will rise as the downturn drags on. Another wave of foreclosures may not be far behind when forbearance periods end, typically in 12 months.

“Guidelines have tightened up immensely, which is to be expected at times like this,” says Matthew Graham, chief operating officer of Mortgage News Daily. “While it’s definitely unfair to borrowers who would make all their payments on time, lenders are adjusting for the higher probability of forbearance.”

About 5% to 20% of prospective borrowers could have trouble getting a mortgage due to the higher standards, says Javier Vivas, realtor.com®’s director of economic research.

Those numbers will likely rise as the recession worsens. Unemployment could top 20% in some worst-case scenarios, and even those who hold on to their jobs could see their salaries fall and lose bonuses, overtime pay, and side gigs. Many of these folks have already ruled out immediate plans to buy a home.

“In the short term it will be a challenge for buyers to qualify for a home mortgage,” says Vivas. “In the mid- and longer term, the bigger concern will be whether they can carry that mortgage through the recession.”

Some lenders are requiring higher credit scores

Many folks with average credit scores, who may have even been pre-approved for a loan at the beginning of the year, may have trouble qualifying for a loan in today’s environment.

Before most folks had heard of COVID-19, credit score requirements started at just 580—or lower in some cases. These were primarily for government-backed loans, such as Federal Housing Administration, U.S. Department of Veterans Affairs, and U.S. Department of Agriculture mortgages. Now, most lenders issuing those loans are asking for credit scores starting between 640 and 680.

“It’s a fairly substantial increase,” says longtime mortgage broker Rocke Andrews, who’s based in Tucson, AZ. He’s also the president of the National Association of Mortgage Brokers. “It hurts a lot of the first-time home buyers.”

Most JPMorgan Chase borrowers will need a minimum 700 credit score—and 20% down—to qualify for a new loan. (There is at least one exception, the DreaMaker program targeted toward low- and moderate-income and first-time home buyers with lower credit scores and down payments.) The bank was the fourth-biggest mortgage lender in 2019, according to Inside Mortgage Finance.

“Due to the economic uncertainty, we are making temporary changes that will allow us to more closely focus on serving our existing customers,” a Chase Home Lending spokesperson said in a statement.

Flagstar Bank and Better.com are also now requiring borrowers to have higher credit scores. Flagstar is asking for 660 scores for FHA loans and 680 for VA and U.S. Department of Agriculture loans. Better.com is asking for minimum 680 scores. Previously, lenders’ minimum scores were 640.

During this crisis, Navy Federal and Better.com have temporarily stopped offering FHA loans altogether.

“Credit policies are tightening for everything. … We don’t want to see another crisis happen when people are getting loans they can’t afford,” says Better.com spokeswoman Tanya Hayre. The online brokerage made nearly 3,000 loans totaling about $1 billion in March. “Hopefully, this will all go back to normal soon.”

Fewer jumbo mortgages are being offered

Fewer lenders are offering jumbo mortgages during this crisis. That’s because for these larger loans, there’s more money on the line if the borrowers go into forbearance or default on their payments. Jumbo loans typically start around $510,000 and go up to just over $765,000 in some of the nation’s most expensive real estate markets.

Banks don’t like to keep loans on their books, because it ties up capital they could be using to make more loans. So they typically bundle up mortgages and sell them to investors in the secondary mortgage. But jumbo loans aren’t backed by Fannie Mae or Freddie Mac. So investors consider them risky, especially in a time when many folks are going into forbearance and not making payments on them, and aren’t buying.

That means banks will have to hold on to those loans if they can’t unload them, which limits how many new loans they can make money from. So some lenders aren’t doing them at least for now—or they’re raising fees to give themselves a financial cushion against a potential default and discourage folks from taking them.

“We did see a really rapid slowdown in that market,” says Joel Kan, an economist at the MBA. “It’s harder to get a jumbo loan, and rates are higher.”

Wells Fargo is still offering the loans to buyers, but will refinance jumbo loans only for its customers with at least $250,000 in assets at a Wells Fargo bank.

“The jumbo market hasn’t disappeared entirely,” says Matthew Gardner, chief economist of Windermere Real Estate. The Seattle-based brokerage has locations in 10 Western states. However, he adds, investors “are turning their attention away from loans that are not guaranteed by the government-sponsored entities” such as Fannie and Freddie.

Self-employed, gig workers and real estate investors may have a harder time

Self-employed, gig workers and real estate investors may also struggle to obtain a mortgage. Many of these are the folks who would normally apply for a non-qualified mortgage because they need to verify their income with bank deposits instead of more traditional W-2 forms, pay stubs, and tax returns.

But these mortgages are deemed riskier—and investors in the secondary mortgage market have little appetite for anything but the safest investments. So fewer lenders are offering them—or they’re upping the cost of these loans to account for the risk.

Those extra fees or charging additional points are “a backhand way of not doing those loans,” says lender Andrews.

Plus, some lenders are discounting self-employed income. That means they might count only a portion of what these borrowers made last year, perhaps 70% or 80%, as qualification for a mortgage. Some aren’t factoring in bonuses, expecting that these folks will earn less money this year with the economy in turmoil.

The discounting of earnings also boosts debt-to-income ratios—another factor that goes into whether someone gets a loan. Lenders traditionally like to see less debt and more money coming in.

Lenders are doing additional income verifications

With folks losing their jobs or getting furloughed every day, lenders are also waiting until the last minute to verify employment and income. So instead of checking in with borrowers’ employers two weeks or 10 days before a closing, they’re doing it a few days before, or even on that day.

“It can be catastrophic if someone loses their source of income right before buying a house,” says longtime mortgage lender Jason Lerner. He’s a vice president at George Mason Mortgage in the Baltimore suburb of Lutherville, MD.

Erika and Ian Rasmussen were set to close on a four-bedroom, two-bathroom home in the seaside town of Greenport, NY, on Long Island. The couple, who live in nearby Port Washington, wanted to use the century-old home as a vacation home and short-term rental property.

But a few days before the closing, Erika, 38, was laid off from her marketing job at an advertising association. This threw the deal into jeopardy, despite her husband’s work as the owner of a zoning consultancy practice and the extra income they earn from a rental property.

Erika had been planning on striking out on her own as a consultant and had picked up a few clients, but the pandemic and layoff threw off her timetable. Her lender wouldn’t factor in her consulting income as she hadn’t yet established those earnings for two years.

“We really scrambled a lot to try to save the deal,” says Erika.

They wound up dipping into their 401(k) accounts to come up with a larger down payment, about 40% of the purchase price, to satisfy their lender. Last week they closed on the property. (Lawmakers recently allowed folks to take out up to $100,000 from their 401(k) accounts due to the crisis. They have three years to repay it before facing the typical early-withdrawal penalties.)

“The unemployment picture has definitely gotten a lot worse and quickly,” says MBA’s Kan. “This is one of those economic events where we really don’t know when it’s going to be over and when things are going to go back to normal.”

The post Applying for a Mortgage? Good Luck! Coronavirus Has Made It Harder To Qualify appeared first on Real Estate News & Insights | realtor.com®.


source https://www.realtor.com/news/trends/coronavirus-is-making-it-harder-for-borrowers-to-get-a-mortgage/

Sunday, 3 May 2020

Friday, 1 May 2020

Your Guide To Moving During The Coronavirus Pandemic

How to handle packing, hiring movers and more, according to experts.

source https://www.huffpost.com/entry/moving-guide-coronavirus_l_5eac49f6c5b65156135cd80f

Celeb Designer LM Pagano Selling Her Topanga Sanctuary for $4.5M

LM Pagano

realtor.com

When you buy the home of a top celebrity designer, you don’t need to worry about the level of taste you’re going to be walking away with.

So it isn’t a stretch to say that designer LM Pagano‘s personal residence—a three-bedroom modern residence tucked up in L.A.’s scenic Topanga Canyon—is in turnkey condition.

For a buyer in search of ready-made style, the home’s on the market for $4.5 million.

The angular and artistic structure was designed by the architect Thomas Edig of Tuna Studio Architecture and completed in 1990. Pagano purchased the place for $2,365,000 in 2013 and spent three years getting the design elements just right.

Pagano told us that the home features a number of her signature stylings. One is a mix of new and old objects throughout the interior spaces. She has also infused the home with a feeling of comfort, with white walls everywhere, and her favorite velvet on display.

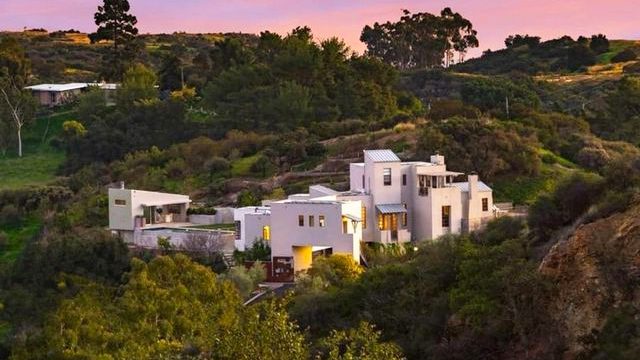
Exterior at dusk

realtor.com

Signature white walls

realtor.com

Great room

realtor.com

Sure enough, there are white walls visible in all the listing photos, along with antique carpets, modern light fixtures, unexpected and whimsical built-ins, as well as lush velvet drapes.

Velvet drapes

realtor.com

The detached studio is an especially interesting mix of old and new. Modern in architectural style, the interior is intriguing, with its variegated wood paneling on the walls and ceiling, and its timeless canyon views.

Studio exterior

realtor.com

Bohemian studio interior with variegated paneling

realtor.com

Even the home’s entry has a spot on the property’s list of unique design features. Pagano says the sculptural metal gates made by her husband are one of her favorite features.

“They are a permanent, gorgeous art installation, unique to this house,” she says.

Custom-made gates

realtor.com

Meanwhile, of course, the 3,640-square-foot main house has no shortage of highlights. Two of its three bedrooms are master suites, with their own bathrooms and private balconies. The multifaceted dwelling has several options for a fourth bedroom and creative use of space.

Bedroom

realtor.com

Bathroom

realtor.com

Private balcony

realtor.com

On 6 acres, the private yard has a dramatic infinity-edge pool that seems to float over a canyon. There’s also a poolhouse with a fireplace and outdoor shower at one end.

The grounds feature gorgeous gardens and over 40 fruit trees. Hiking trails branch out all over the hillsides, and a quaint bridge spans a seasonal brook.

Pool and poolhouse

realtor.com

With so much style and tranquility all on one property, we wondered how Pagano can part with the place.

“I haven’t figured that out yet,” she says. “But I truly thought I couldn’t leave my last house, and ended up loving this one even more. I am always up for the next adventure.”

LM Pagano house and pool

realtor.com

Pagano’s designs for clients like Johnny Depp, Nicolas Cage, and Matthew Perry have been featured in a number of national publications.

Of her work with celebrities, she told us she loves to put the pieces together to create cool design.

“I am influenced by my clients and their personalities. I influence or guide them [after] I figure out the secret to their style,” she says.

“They may know the flowers they like, but not how to gather them up and make a spectacular bouquet. Or which details to leave out. I have to find the key and unlock it.”

Greg Holcomb and Cassandra Petersen at Compass and Nancy Nelms at Snyder Sutton Real Estate have the listing.

The post Celeb Designer LM Pagano Selling Her Topanga Sanctuary for $4.5M appeared first on Real Estate News & Insights | realtor.com®.


source https://www.realtor.com/news/unique-homes/lm-pagano-selling-her-topanga-home/

‘House Party’ Podcast: Coronavirus Myths, Debunked; Jay Cutler and Kristin Cavallari’s Divorce and the House They Can’t Sell

House Party podcast ep 60

Getty Images; realtor.com

“House Party” is realtor.com®’s official podcast about the overlapping worlds of real estate and pop culture, hosted by Natalie Way, Erik Gunther, and Rachel Stults. Click the player above to hear our takes on this week’s hot topics.

There’s a lot of internet noise about COVID-19, and sometimes it can feel impossible to know what’s true and what’s not. Will the novel coronavirus get inside your open windows? Should you microwave your mail to kill the virus? On this week’s episode, we debunk the most common household coronavirus myths that you should stop believing immediately.

Other topics we cover:

  • Jay Cutler and Kristin Cavallari just filed for divorce, but their Nashville, TN, mansion has been on the market for two years. What happens to the estate now?
  • Tom Brady accidentally “trespasses” in Tampa, FL—and we learned how easily it can happen to you, too!
  • Bill and Melinda Gates buy a breathtaking $43 million beach house outside San Diego.
  • And, as always, we highlight our week’s celebrity real estate winner and loser.

Ready to listen? Subscribe on Apple Podcasts, Google Play Music, Spotify, or wherever you get your podcasts. And please: Throw us a five-star rating if you like what you hear. The more good ratings and reviews we have, the easier it is for people to find us.

Want to chime in? Have your own crazy home-related story you’re dying to share? We’re all ears, eagerly waiting to discuss all of your burning real estate questions on “The Mailbox” segment. Email us at podcast@realtor.com, follow us on Facebook, or tweet us @housepartypod on Twitter.

The post ‘House Party’ Podcast: Coronavirus Myths, Debunked; Jay Cutler and Kristin Cavallari’s Divorce and the House They Can’t Sell appeared first on Real Estate News & Insights | realtor.com®.


source https://www.realtor.com/news/podcast/episode-60-house-party-podcast/